Health care is one of the expenses that can become increasingly important as you approach and move through retirement. While many parts of a financial plan can be estimated with some predictability, future medical expenses can be more difficult to anticipate.
Recent changes surrounding Health Savings Accounts have brought additional attention to the role health care expenses play in financial planning. For 2026, HSA contribution limits increased, and new rules expanded eligibility for certain individuals.
These changes are a timely reminder that preparing for future health-related expenses should be part of your broader retirement strategy.
Health Care Is Part of Retirement Planning
When thinking about retirement expenses, it is easy to focus on housing, travel, and everyday spending. Health care deserves a place in that conversation as well.
Even with Medicare or other insurance coverage, retirees may still be responsible for premiums, deductibles, prescription medications, dental and vision care, and other expenses that may not be fully covered.
Planning for these costs ahead of time can help reduce the likelihood that an unexpected medical expense will require significant withdrawals from investments or other retirement assets.
Plan for How Health Care Costs Will Be Funded
A comprehensive retirement plan should account for how future health-related expenses will be paid without unnecessarily disrupting the rest of your financial strategy.
That may include maintaining appropriate cash reserves, setting aside specific assets for medical expenses, reviewing insurance coverage, and considering how Medicare premiums and other out-of-pocket costs fit into your retirement income needs.
The goal is to avoid having an unexpected medical expense force a larger withdrawal from investments at an inconvenient time. Building health care costs into your retirement strategy can help create greater flexibility and protect the assets supporting your lifestyle.
Use the Right Accounts and Resources
For those who are eligible, a Health Savings Account can be a valuable part of long-term health care planning. Contributions may receive favorable tax treatment, assets can potentially grow over time, and qualified withdrawals can be used for eligible medical expenses.
Health care planning should also include reviewing Medicare choices, insurance coverage, and potential long-term care needs as your circumstances change.
Rather than treating these decisions separately, they should work alongside your retirement income, investment, and tax strategies. Coordinating each part of the plan can help you prepare for future health care needs while keeping your broader financial goals on track.
Consider the Costs Beyond Routine Care
Planning for health care is about more than budgeting for annual doctor visits.
As you look further into retirement, your plan may also need to consider prescription expenses, specialized care, changes in insurance premiums, and the possibility of needing additional assistance later in life.
Long-term care deserves particular attention. Medicare generally does not cover most long-term custodial care, which means families may need to determine in advance how those expenses would be handled.
Preparing for different possibilities can provide greater flexibility if your needs eventually change.
Protecting Your Retirement Assets
Unexpected health-related expenses can have an impact beyond the medical bill itself.
A large withdrawal from a retirement account could affect your taxable income, investment strategy, or the assets available to support future years of retirement. Depending on your circumstances, it could also affect the wealth you ultimately intend to leave to your family or other beneficiaries.
Planning ahead allows health care expenses to be considered before they become urgent. The goal is to have resources available without unnecessarily disrupting the rest of your financial plan.
Your Needs Will Change Over Time
Just as your investment strategy evolves throughout retirement, your approach to health care planning may need to evolve as well.
Changes in your health, family circumstances, insurance coverage, retirement income, or financial resources may all affect your strategy.
This is why health-related costs should be reviewed periodically as part of your overall financial plan rather than addressed only when a medical need arises.
Planning Today for Greater Flexibility Tomorrow
No one can know exactly what their future health care needs will look like. What you can do is build flexibility into your financial plan.
By considering health care expenses alongside retirement income, investments, insurance, taxes, and long-term care planning, you can create a strategy designed to protect both your lifestyle and the assets you have spent years building.
Planning for health-related costs is ultimately about more than preparing for medical bills. It is about helping your financial plan remain strong and adaptable throughout retirement.
Health care expenses are already an important consideration in your financial plan. If your needs, coverage, or retirement goals have changed, give us a call so we can review your strategy and make sure your plan continues to reflect your priorities.
Golf Tip of the Week
A Balanced Finish
A balanced finish is one of the simplest indicators of a good golf swing. If you’re off balance at the end of your swing, it often means something went wrong earlier — usually with tempo or weight transfer.
After impact, your weight should finish mostly on your lead foot with your chest facing the target. You should be able to hold your finish position comfortably for a few seconds.
A helpful practice habit is to pause and hold your finish after every swing on the range. If you can stay balanced without stepping or wobbling, your swing likely stayed in sequence.
Balance creates consistency. When your swing finishes in control, the ball usually follows suit.
Golf Tip adapted from Golf Digest. Read the full article here: What the Pros Know: Don’t Cheat Your Finish
Recipe Tip of the Week
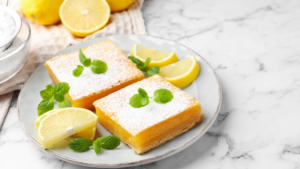
Lemon Bars
Ingredients
Crust
- 1 cup unsalted butter, softened
- ½ cup granulated sugar
- 2 cups all-purpose flour
- Pinch of salt
Filling
- 4 large eggs
- 1 ½ cups granulated sugar
- ¼ cup all-purpose flour
- ⅔ cup fresh lemon juice
- Powdered sugar for dusting
Instructions
Preheat oven to 350°F.
Mix butter, sugar, flour, and salt until crumbly. Press evenly into a greased 9×13 baking pan.
Bake the crust for about 15–18 minutes until lightly golden.
While the crust bakes, whisk eggs, sugar, flour, and lemon juice until smooth.
Pour the filling over the warm crust and return to the oven. Bake another 18–20 minutes until the center is set.
Cool completely, then dust with powdered sugar before cutting into squares.
Tip of the Week
For clean slices, chill the lemon bars for about an hour before cutting.
Bright, sweet, and slightly tart — perfect for summer gatherings.
Recipe adapted from Food Network. See full recipe here: Classic Lemon Bars
Travel Tip of the Week
Cannon Beach, Oregon: Pacific Northwest Coastal Escape
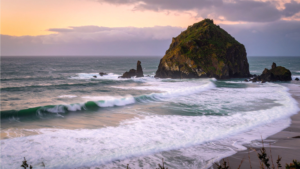
August is one of the best months to visit Cannon Beach. Temperatures are typically mild, often in the mid-60s to low 70s, making it a refreshing break from intense summer heat in many parts of the country.
The town is known for its iconic Haystack Rock, dramatic coastal scenery, and relaxed small-town charm. Visitors can enjoy long beach walks, explore tide pools, browse local art galleries, or simply relax while watching the Pacific waves roll in.
Why It’s Great in August
- Cool coastal temperatures
- Stunning ocean views and dramatic rock formations
- Walkable beach town atmosphere
- Beautiful sunsets over the Pacific
Cannon Beach offers a peaceful coastal retreat where the focus is simple: fresh air, scenic views, and a slower pace.
Travel tip adapted from Travel + Leisure. Read the full article here: This Small Oregon Beach Town Has a 235-foot-tall Sea Stack, Wooded Hiking Trails, Craft Breweries, and Delicious Seafood
Copyright © 2026. BCA Private Wealth. All rights reserved.
Our mailing address is:
BCA Private Wealth
15 Halton Green Way
Greenville, SC 29607
Disclosure:
BCA is a Securities and Exchange Commission registered investment advisor. The advisory services of BCA Private Wealth are not made available in any jurisdiction in which BCA Private Wealth is not registered or is otherwise exempt from registration.
Please review BCA Private Wealth Disclosure Brochure for a complete explanation of fees. Investing involves risks. Investments are not guaranteed and may lose value.
This material is prepared by BCA Private Wealth for informational purposes only. It is not intended to serve as a substitute for personalized investment advice or as a recommendation or solicitation or any particular security, strategy, or investment product.
No representation is being made that any account will or is likely to achieve future profits or losses similar to those shown. You should not assume that investment decisions we make in the future will be profitable or equal the investment performance of the past. Past performance does not indicate future results.
Sources
IRS: 2026 Health Savings Account Limits
Medicare: Long Term Care Coverage