The end of the year may still feel far away, but when it comes to tax planning, waiting until December can limit your options.
Tax planning is most effective when it is proactive. Reviewing your income, investments, retirement accounts, charitable giving, and other financial decisions now provides time to identify opportunities and make thoughtful adjustments before December 31.
For 2026, updated tax brackets, deductions, and retirement contribution limits make this an especially good time to review your strategy.
Start With Your Income
Your income can look very different from one year to the next, particularly in retirement or when a significant financial event occurs.
Investment gains, required minimum distributions, business income, bonuses, stock compensation, retirement account withdrawals, and other sources can all influence your taxable income.
Reviewing where you currently stand can help you estimate your income for the full year and determine whether there are planning opportunities before the end of the year.
Review Your Investment Portfolio
Taxes should not drive every investment decision, but they are an important part of managing a portfolio.
If you have investments that have declined in value, tax loss harvesting may provide an opportunity to offset realized capital gains. At the same time, appreciated investments may require additional planning before they are sold.
This is also an opportunity to review whether your portfolio remains aligned with your investment strategy. Rebalancing, managing gains and losses, and evaluating concentrated positions can all be considered together rather than as separate decisions.
Evaluating Retirement Account Strategies
Retirement accounts can provide several year-end planning opportunities.
For 2026, the employee contribution limit for 401(k), 403(b), and most governmental 457 plans are $24,500. Those ages 50 and older may generally contribute an additional $8,000, while individuals ages 60 through 63 may qualify for a higher catch-up contribution of $11,250.
The IRA contribution limit is $7,500 for 2026, with an additional $1,100 available for those age 50 and older.
Depending on your circumstances, this may be a good time to review whether you are on track with your retirement contributions and whether adjustments should be made before the end of the year.
Consider Roth Conversion Opportunities
A Roth conversion can move assets from a traditional retirement account into a Roth IRA. The converted amount is generally included in taxable income for the year, which makes tax planning particularly important.
Rather than deciding on a conversion in isolation, consider your projected taxable income, current tax bracket, future retirement income, required minimum distributions, and long-term estate planning goals.
For some individuals, intentionally recognizing additional income in a particular year may support a broader long-term tax strategy.
Think Strategically About Charitable Giving
If charitable giving is already part of your financial plan, the way you give can matter.
Depending on your circumstances, strategies involving appreciated securities, donor-advised funds, or qualified charitable distributions may be worth discussing.
Planning earlier in the year provides more time to coordinate charitable intentions with your investment and tax strategies rather than rushing to complete gifts in the final days of December.
Look Beyond This Year’s Tax Bill
Effective tax planning is not simply about paying the least amount of tax this year.
Sometimes a decision that increases taxes today could potentially improve your financial position over the long term. Other times, accelerating or delaying income, deductions, or investment gains may make sense.
The goal is to understand how today’s decisions affect not only your 2026 tax return, but also your retirement income, investments, estate plan, and the wealth you ultimately intend to transfer.
Give Yourself Time to Plan
By December, some planning opportunities may already have passed or become difficult to implement.
Starting now gives you and your financial professionals time to review your projected income, evaluate your portfolio, coordinate with your tax professional, and determine which strategies are appropriate for your individual situation.
Your tax strategy should work alongside the rest of your financial plan, not separately from it.
A thoughtful review now can help you approach the final months of 2026 with a clearer picture of where you stand and what decisions may still need to be made.
Year-end tax planning is already an important part of the financial planning process. If your income, investments, charitable giving, or financial circumstances have changed this year, give us a call so we can review your strategy and identify any planning opportunities before year-end.
Golf Tip of the Week
Swing with Confidence
Many poor golf shots happen before the swing even begins. Doubt about club selection can lead to tentative swings and inconsistent contact.
Before stepping up to the ball, take time to assess distance, wind, and elevation. Once you choose your club, commit fully to the decision. Confidence allows you to swing freely and maintain your natural tempo.
A consistent pre-shot routine helps reinforce that commitment. Visualize the shot, take a practice swing, and step in with a clear plan.
Golf rewards decisiveness. When you trust your club selection and swing with conviction, your chances of solid contact and better results increase dramatically.
Golf Tip adapted from Golf Digest. Read the full article here: Confidence kills: What if everything you’ve been told to think is wrong?
Recipe Tip of the Week
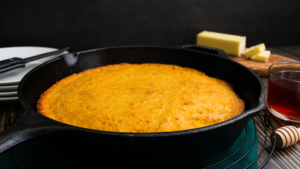
Honey Butter Skillet Cornbread
Ingredients
- 1 cup yellow cornmeal
- 1 cup all-purpose flour
- ¼ cup granulated sugar
- 1 tbsp baking powder
- ½ tsp salt
- 1 cup milk
- 2 large eggs
- ½ cup unsalted butter, melted
- 2 tbsp honey
Honey Butter
- ¼ cup softened butter
- 2 tbsp honey
Instructions
Preheat oven to 400°F. Place a cast iron skillet in the oven to warm.
In a bowl, whisk together cornmeal, flour, sugar, baking powder, and salt.
In another bowl, mix milk, eggs, melted butter, and honey. Combine with the dry ingredients until just blended.
Carefully remove the hot skillet, lightly grease it, and pour in the batter.
Bake 18–22 minutes until golden and set in the center.
Mix butter and honey together and spread over warm cornbread before serving.
Tip of the Week
A hot skillet helps create that classic crispy golden edge while keeping the inside soft and tender.
Sweet, buttery, and perfect alongside barbecue, chili, or a cozy dinner.
Recipe adapted from food network. See full recipe here: Cornbread with Honey Butter
Travel Tip of the Week
Try Traveling to Portugal
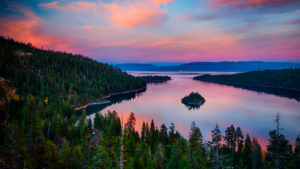
September is one of the best times to visit Lake Tahoe. Temperatures are typically in the 70s and low 80s, offering comfortable weather for outdoor activities and lakeside relaxation.
Visitors can enjoy scenic boat rides, lakeside walking paths, and panoramic mountain views without needing strenuous hikes. The clear blue water and surrounding alpine scenery make it one of the most picturesque summer destinations in the United States.
Why It’s Great in September
- Warm days and cool evenings
- Crystal-clear alpine lake views
- Scenic drives and boat tours
- Relaxed mountain-town atmosphere
Lake Tahoe offers the perfect balance of fresh mountain air and waterfront relaxation — ideal for a peaceful late-summer getaway.
Travel tip adapted from Visit lake tahoe. Read the full article here: Welcome to Lake Tahoe
Copyright © 2026. BCA Private Wealth. All rights reserved.
Our mailing address is:
BCA Private Wealth
15 Halton Green Way
Greenville, SC 29607
Disclosure:
BCA is a Securities and Exchange Commission registered investment advisor. The advisory services of BCA Private Wealth are not made available in any jurisdiction in which BCA Private Wealth is not registered or is otherwise exempt from registration.
Please review BCA Private Wealth Disclosure Brochure for a complete explanation of fees. Investing involves risks. Investments are not guaranteed and may lose value.
This material is prepared by BCA Private Wealth for informational purposes only. It is not intended to serve as a substitute for personalized investment advice or as a recommendation or solicitation or any particular security, strategy, or investment product.
No representation is being made that any account will or is likely to achieve future profits or losses similar to those shown. You should not assume that investment decisions we make in the future will be profitable or equal the investment performance of the past. Past performance does not indicate future results.